
Medically reviewed by: Dr. Peter Scheid, Medical Director
Let’s be honest: understanding health insurance can be confusing on a normal day, and it’s even more complicated when you or a loved one is about to seek treatment for addiction. “Is this covered?” “Will my bill be higher than what I expected?” “What if I have to switch providers in the middle of treatment?” All are good questions, and you’re not alone in your questions. The good news is that all you have to do to check your rehab insurance benefits is to pick up the phone, do a little research and ask the right questions – it is way easier than you think! Here’s exactly how to do it.
Why Verifying Your Insurance Benefits Matters Before You Start Treatment
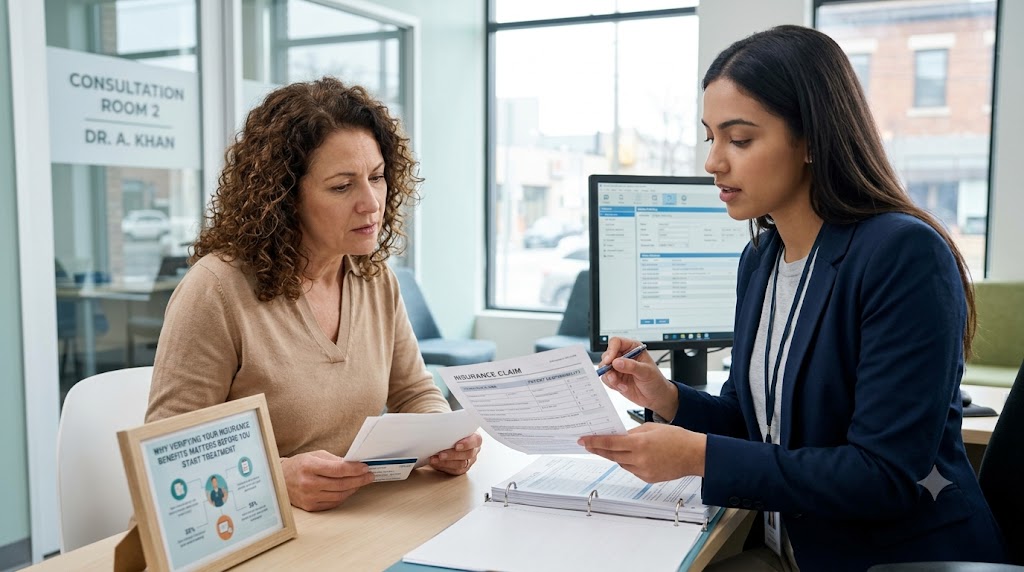
Most people think that if you have insurance, your treatment is covered. That’s not always the case. You can find policies that cover detox and residential treatment or those that cover only outpatient programs. Others require pre-authorization or only pay for a certain number of days.
Pre-Approving: Helps you steer clear of Financial surprises, to pick a program that aligns with your plan, and to eliminate stress at a time you need to get well. Being familiar with your numbers helps you to make decisions with assurance, not anxiety.
Gather the Right Information Before You Make the Call
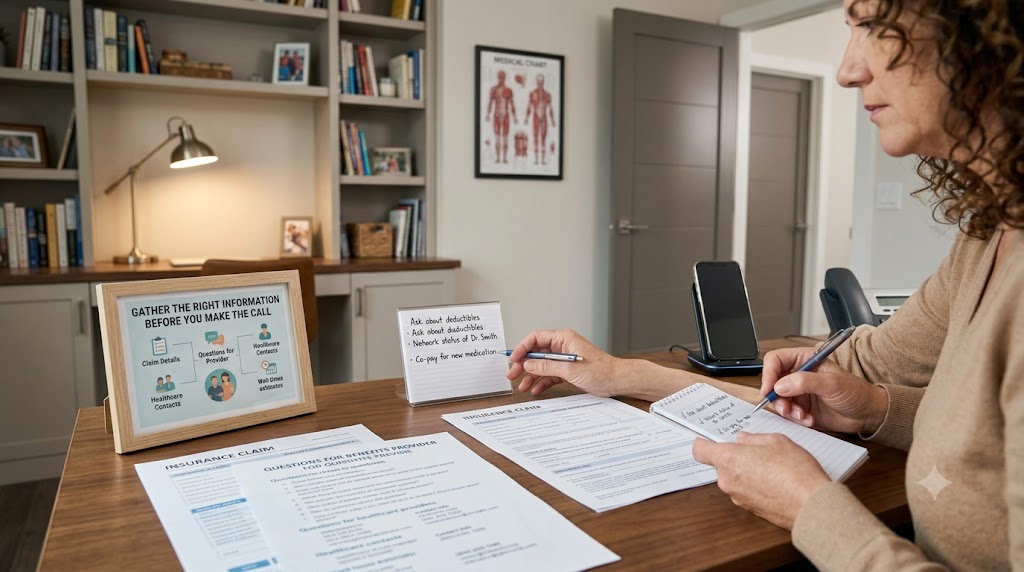
Before you call your insurance company, you’ll want to have a few things handy:
- Your insurance card (front and back)
- Your member ID and group number
- The policyholder’s name and date of birth if the plan isn’t in your name
- The name and number of the treatment center you’re calling to inquire about.
- A pen and paper/notes app for jotting down details
Being prepared will make the call quicker and prevent you from having to be transferred around.
Call the Member Services Number on Your Insurance Card
The fastest way to verify your benefits is to call the member services phone number on the back of your card. Let the representative know that you want to verify the benefits for a substance use disorder treatment (sometimes known as behavioral health) benefits. Some benefit plans forward these calls to a different behavioral health department.
Another place to look is your insurer’s website – many plans now include benefit summaries. But a phone call is ideal, as you can get answers to follow-up questions immediately.
Key Questions to Ask Your Insurance Provider About Rehab Coverage
This is what it’s all about. So, ask yourself these questions and jot down the answers:
- What levels of care does it cover? Inquire about the types of treatment such as medical detox, residential treatment, partial hospitalization, intensive outpatient and outpatient.
- Does the practice participate? Out-of-network practices often charge a lot more, although a plan might have a limited out-of-network benefit.
- What is my deductible and how much have I met? This is the amount you will have to pay before your insurance begins to pay.
- What are my copays or coinsurances? These are your share of costs after meeting your deductible.
- How much is my out-of-pocket max? The maximum amount that you have to pay during a plan year before the insurance company covers the rest.
- Have you obtained pre-authorization? A lot of strategies should be pre-approved to treat.
- Is there a maximum number of days or visits? Certain plans limit the number of inpatient stays or appointments.
- Am I required to have a referral or doctors’ examination? Some plans need formal diagnosis or medical necessity determination.
Get the rep’s name and a call reference number before you end the call. That record could become a crucial document if a dispute arises.
Understand Common Insurance Terms You’ll Hear
Insurance jargon may as well be a foreign language. Here are a handful of terms we see most often:
- Pre-authorization: Consent from your insurer in advance of treatment.
- Medical necessity: How your insurer determines whether a service is suitable for your particular condition.
- Network: Providers that are contracted with your insurance company.
- Explanation of Benefits (EOB): A statement of how much was charged, how much your insurance paid, and how much you owe.
If a term is used that you are not familiar with, request that the representative define it. They can do that.
Let the Treatment Center Verify Your Benefits for You
You don’t have to handle this on your own. Reputable rehab centers provide free insurance verification. Provide them with your insurance information, and their admissions department will get in touch with your insurer, understand your coverage, and let you know your estimated costs in simple terms.
It’s usually quicker and more accurate to have the admissions staff make this call, because they’ve done it before and they know what questions are worth asking. It also doesn’t lock you into anything. You’re just collecting information.
Know Your Rights Under Federal Parity Laws
In the United States, the Mental Health Parity and Addiction Equity Act (MHPAEA) was passed in 2008 to mandate that certain health insurance plans pay for substance use disorder treatment, at parity with medical and surgical benefits. The Affordable Care Act (ACA) also requires that many plans cover these services as one of its essential health benefits.
This doesn’t mean all plans include all services, and coverage specifics are subject to your plan type and state. But if you feel you’ve been wrongfully denied coverage, you may file an appeal. Inquire with your insurer about how to file an appeal, and ask your provider for any documentation you may need.
What to Do If Coverage Is Limited or Denied
Rejection doesn’t always mean the end of the process. But you can:
- Write the reason and a request for reconsideration.
- File an internal appeal with your insurer
- Request that your doctor or care team write a letter of medical necessity.
- External review if internal appeal not successful
- Ask about payment plans, sliding scale fees, or financing options
Note that perseverance can be rewarded and many people are successful at the appeal level.
Take the Next Step With Confidence
Reviewing your rehab insurance benefits might seem like just another obstacle, but it’s really only a few strategic conversations. Collect your data, ask the important questions, record the conversations, and use your treatment team as a resource. After you know what your coverage includes, you can get down to the business of healing.
Before you make a decision, you can contact Harbor Detox to find out about your insurance benefits and coverage with us. This is a hassle-free initial step that you can easily take before you start your recovery and truly deserve to have answers when you get started.
Contact Details
- Company Name: Harbor Detox
- Phone: (888) 793-8002
- Email ID: info@harbordetox.com
- Address: 24832 La Paz Ave, Suite A, Dana Point, CA 92629, USA
FAQs
Will my insurance actually cover rehab, or am I just assuming it does?
It depends on your policy. Some substance use treatments, such as detox, can be covered by most policies, but the specifics of coverage (residential, outpatient, and duration of each) can vary significantly. The only way to get a definitive answer is to call your insurance company or have a treatment center check your benefits for you.
How long does it take to check my rehab insurance benefits?
It typically takes 15-30 minutes to call your insurer, including waiting on hold. When you have a treatment center confirm for you, you can usually find out within the same day or even the same hour or two.
Do I have to tell my employer I’m checking my benefits?
No. Your call to an insurance company or to a treatment center to check coverage cannot reach your employer. Laws protect patient confidentiality, and insurance companies have to comply with regulations that keep your health information private. If this concerns you, ask the insurer how your information is used.
What if I don’t have a deductible met yet? Does that mean I’ll pay everything?
Not quite, but you might have a bigger bill to start. You pay for services out of your pocket until you reach your deductible. Once you’ve hit it, you and the insurance company split the cost via copays or coinsurance. Check with your insurer to see if you’ve paid some of your deductible this year.
What does “in-network” really mean, and why should I care?
The facility is in your insurance network which is preferable because your costs are likely to be lower. If they are out of your network, they might still be covered, but likely at a higher cost. It is worth asking both questions.
Is pre-authorization really necessary?
For some plans, yes. Not ticking the box might mean the insurer won’t pay even for services you are entitled to. The staff at the treatment centre’s admissions desk will probably be able to sort this form out with you, rather than leaving it to you to chase.